
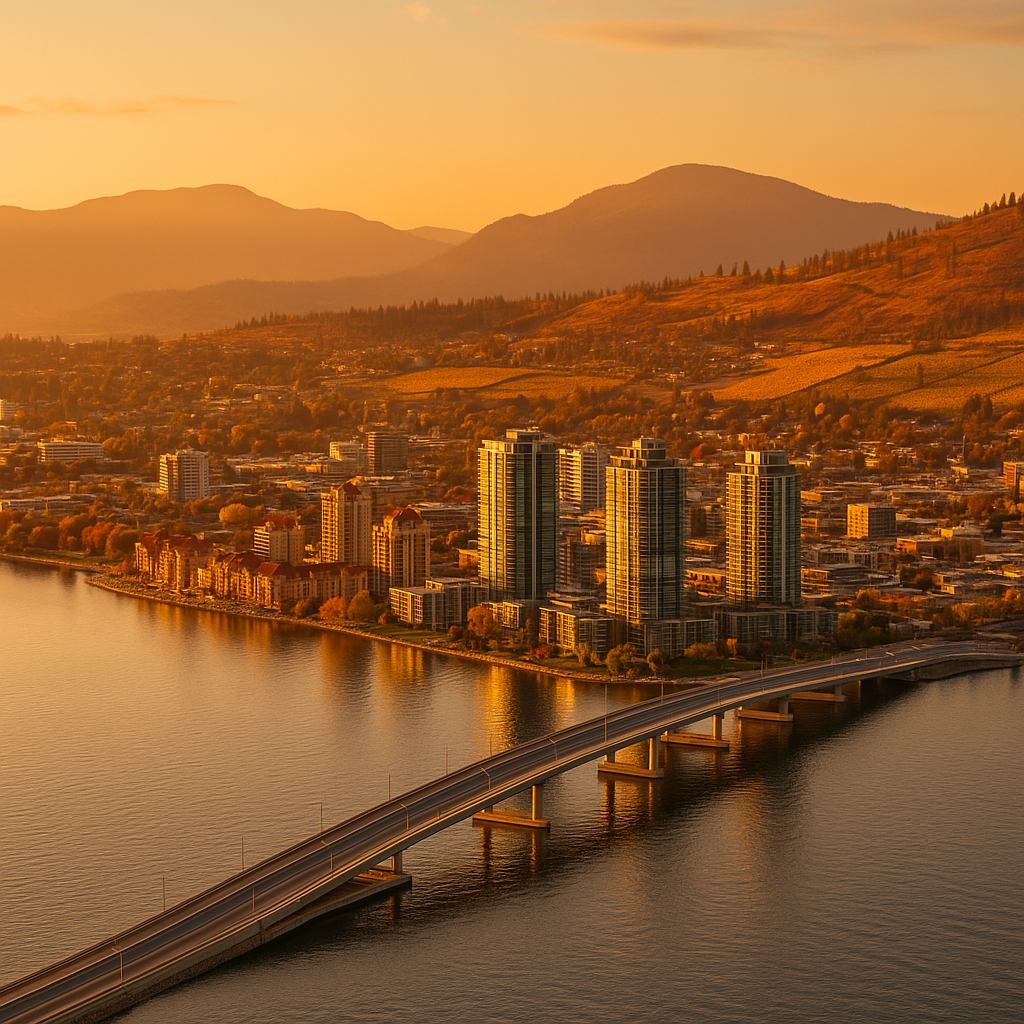
The Kelowna real estate market is entering the final quarter of 2026 in a very different position than it did just eighteen months ago. After a punishing rate cycle, a wave of speculation-tax adjustments, and a slower-than-expected recovery in luxury waterfront, the Okanagan is settling into what many analysts are calling a “disciplined rebound.” For investors evaluating where to deploy capital before year-end, Kelowna is once again looking like one of the most compelling mid-sized markets in Western Canada.
This article breaks down what has actually happened in the Kelowna real estate market through September 2026, where the numbers point next, and—most importantly—the specific investor plays that make sense right now.
Where the Kelowna Real Estate Market Stands in September 2026
The current cycle is best understood in three phases: the 2022–2023 correction, the 2024–2025 stabilization, and the 2026 selective rebound. As of this month, the Association of Interior REALTORS® is reporting that the Central Okanagan benchmark single-family price is hovering in the low-$1.05M range, up modestly year over year but still roughly 8–10% below the 2022 peak. Condos are the standout, with benchmark values pushing back through the $520K mark on the back of strong rental demand and constrained new supply.
Sales volume in August and early September 2026 is running noticeably ahead of the same period last year. Days on market have compressed from the mid-70s in 2024 to the mid-40s today for well-priced product under $900K. Above $2M, the story is different: inventory remains elevated, and buyers are firmly in control.
Key 2026 Market Signals Investors Should Watch
- Interest rates: The Bank of Canada’s overnight rate sits at 2.50% following the summer cuts, with fixed five-year insured mortgages available in the high 3s.
- Population growth: The Central Okanagan added roughly 12,000 net new residents over the last 12 months, one of the fastest per-capita growth rates in BC.
- Rental vacancy: CMHC’s spring 2026 report pegged Kelowna’s purpose-built vacancy at 1.9%—tighter than Vancouver.
- New construction starts: Down roughly 22% year over year, tightening the medium-term supply pipeline.
- Short-term rental rules: The provincial STR framework remains in force, funneling demand into long-term rentals and reshaping the investment thesis around cash flow.
Why Kelowna Is Back on Institutional Radars
For years, the Kelowna real estate market was viewed primarily as a lifestyle and retirement play. That narrative is shifting. UBC Okanagan’s enrollment has now crossed 15,500 students, the tech corridor around Innovation Centre keeps expanding, and YLW Airport recently confirmed its terminal expansion timeline for completion in 2028. Combined with a mature medical hub anchored by Kelowna General Hospital, the city now offers the type of diversified economic base that institutional and semi-institutional capital wants to see before committing.
Add to that the migration story. StatsCan’s latest interprovincial data shows the Okanagan continuing to attract net inflows from Alberta and Ontario, with a growing share of remote-work households in the 30–45 age bracket. These are renters and buyers with income, and they are landing in a city where housing starts have not kept pace.
The Numbers: What Investors Are Actually Underwriting in 2026
Cash Flow Reality Check
Let’s be blunt: at 2022 prices and 2022 rates, almost nothing in Kelowna cash-flowed on a traditional 20% down purchase. In September 2026, that math has finally shifted. A well-selected two-bedroom condo in the $475K–$525K range in Lower Mission, Glenmore, or Rutland South can now rent for $2,450–$2,750 per month. With a 25% down payment and a five-year fixed near 4.0%, investors are penciling in modest positive cash flow of $75–$225 per month after strata, taxes, insurance, and a maintenance reserve.
That’s not a home run, but it’s the first time in nearly four years that new-acquisition condos in the Kelowna real estate market are cash-flow neutral or better on day one, and it’s the reason phones at local property managers have started ringing again.
Appreciation Assumptions
Most Kelowna-focused analysts are modeling 4–6% annual price growth over the 2027–2029 window, driven by supply constraints and continued in-migration. That is well below the double-digit years of 2020–2022, but paired with cash flow and mortgage paydown, levered internal rates of return in the 12–16% range are realistic for disciplined buyers.
Neighbourhoods Worth a Serious Look Right Now
Rutland – The Yield Play
Rutland continues to offer the best gross rent multiples in the Central Okanagan. Older townhomes and legal-suite houses trade at a meaningful discount to Mission or Lakeshore product while renting for nearly comparable amounts on a per-bedroom basis. With the Highway 33 corridor upgrades underway and new transit priority lanes, the medium-term appreciation case is strengthening.
Glenmore and North Clifton – Family Rentals
Glenmore attracts long-term family tenants who stay put for years. Vacancy risk is low, and single-family homes with self-contained secondary suites are the sweet spot. Expect entry prices from $1.05M to $1.25M with combined rents of $4,200–$4,800 per month.
Lower Mission – The Blue-Chip Hold
Lower Mission remains the prestige address. Yields are compressed, but if your thesis is a 10-year hold with strong land value and lifestyle-driven demand, this is where legacy money sits. Watch for waterfront-adjacent condo product listed since spring 2026—several buildings are quietly negotiable right now.
Downtown – The Contrarian Bet
Downtown Kelowna took the hardest hit from the STR restrictions, and inventory built up quickly through 2024. In 2026, we are seeing units in Bertram, Ella, and One Water trade 12–18% below their pre-sale prices. For investors comfortable with a longer stabilization horizon, this is where the deepest value in the entire Kelowna real estate market currently sits.
Risks Investors Should Not Ignore
No market is a one-way bet, and Kelowna has genuine risks that any serious investor should stress-test.
- Wildfire and insurance: Insurance premiums for properties in the wildland-urban interface have risen 30–60% since 2023. Underwrite realistically and consider FireSmart-certified properties.
- Provincial policy shifts: The BC government has shown willingness to move quickly on housing policy—flipping taxes, STR rules, and zoning overrides can all change your pro forma overnight.
- Concentration risk in tourism: A meaningful slice of local employment remains tied to hospitality and wine. A prolonged consumer slowdown would show up in rents first.
- Concessions in new construction: Developers are still offering assignments, decorating allowances, and rate buydowns. Resale investors need to price against that competition.
Financing the Deal in Late 2026
Financing conditions have loosened materially since the start of the year. Insured five-year fixed rates in the high 3s, uninsured rental-property rates in the low-to-mid 4s, and lender appetite for small-scale investors has returned. Credit unions across the Okanagan—Interior Savings, Valley First, and Prospera—are once again writing rental portfolios up to five doors with 20% down on approved covenants.
Investors should also revisit the multiplex financing opportunity. Under Kelowna’s updated zoning bylaw aligned with the provincial Small-Scale Multi-Unit Housing legislation, most single-family lots can now accommodate three to four units. CMHC’s MLI Select program continues to offer up to 95% loan-to-cost for qualifying purpose-built rental projects meeting affordability, energy, or accessibility criteria—an unusually powerful tool for infill developers in 2026.
How to Position Your Portfolio Before Year-End 2026
With three months left in the year, here is the strategic checklist I would run if I were deploying fresh capital into the Kelowna real estate market this quarter:
- Get pre-approved this week. Rate holds are 120 days. Locking a sub-4% fixed now protects you if the Bank of Canada pauses.
- Focus on cash-flow-positive product under $600K. That is where the tenant pool is deepest and the exit liquidity is best.
- Negotiate hard on any listing older than 60 days. Sellers who missed the spring window are increasingly motivated as they approach year-end.
- Model your pro forma with 4.5% mortgage renewal rates. Do not underwrite today’s rates five years forward.
- Insist on a proper rental appraisal, not the listing agent’s optimism. Kelowna rents softened 3–4% in the last twelve months in some pockets.
The Bottom Line for Investors
The Kelowna real estate market in September 2026 is not a screaming buy, but it is a legitimate opportunity for investors with a three-to-seven-year horizon. Rates have come down, supply is constrained, migration is real, and—for the first time since the pandemic distortion—deals actually pencil. The window between now and the spring 2027 selling season is when patient, well-financed buyers typically win in the Okanagan. Do the work, underwrite conservatively, and this cycle can be the one you look back on as the entry point.
Get a FREE Comparative Market Analysis in today's market.What's your home worth?
Browse Other Communities
Enjoy this blog post? Click here to subscribe for updates
Leave A Comment